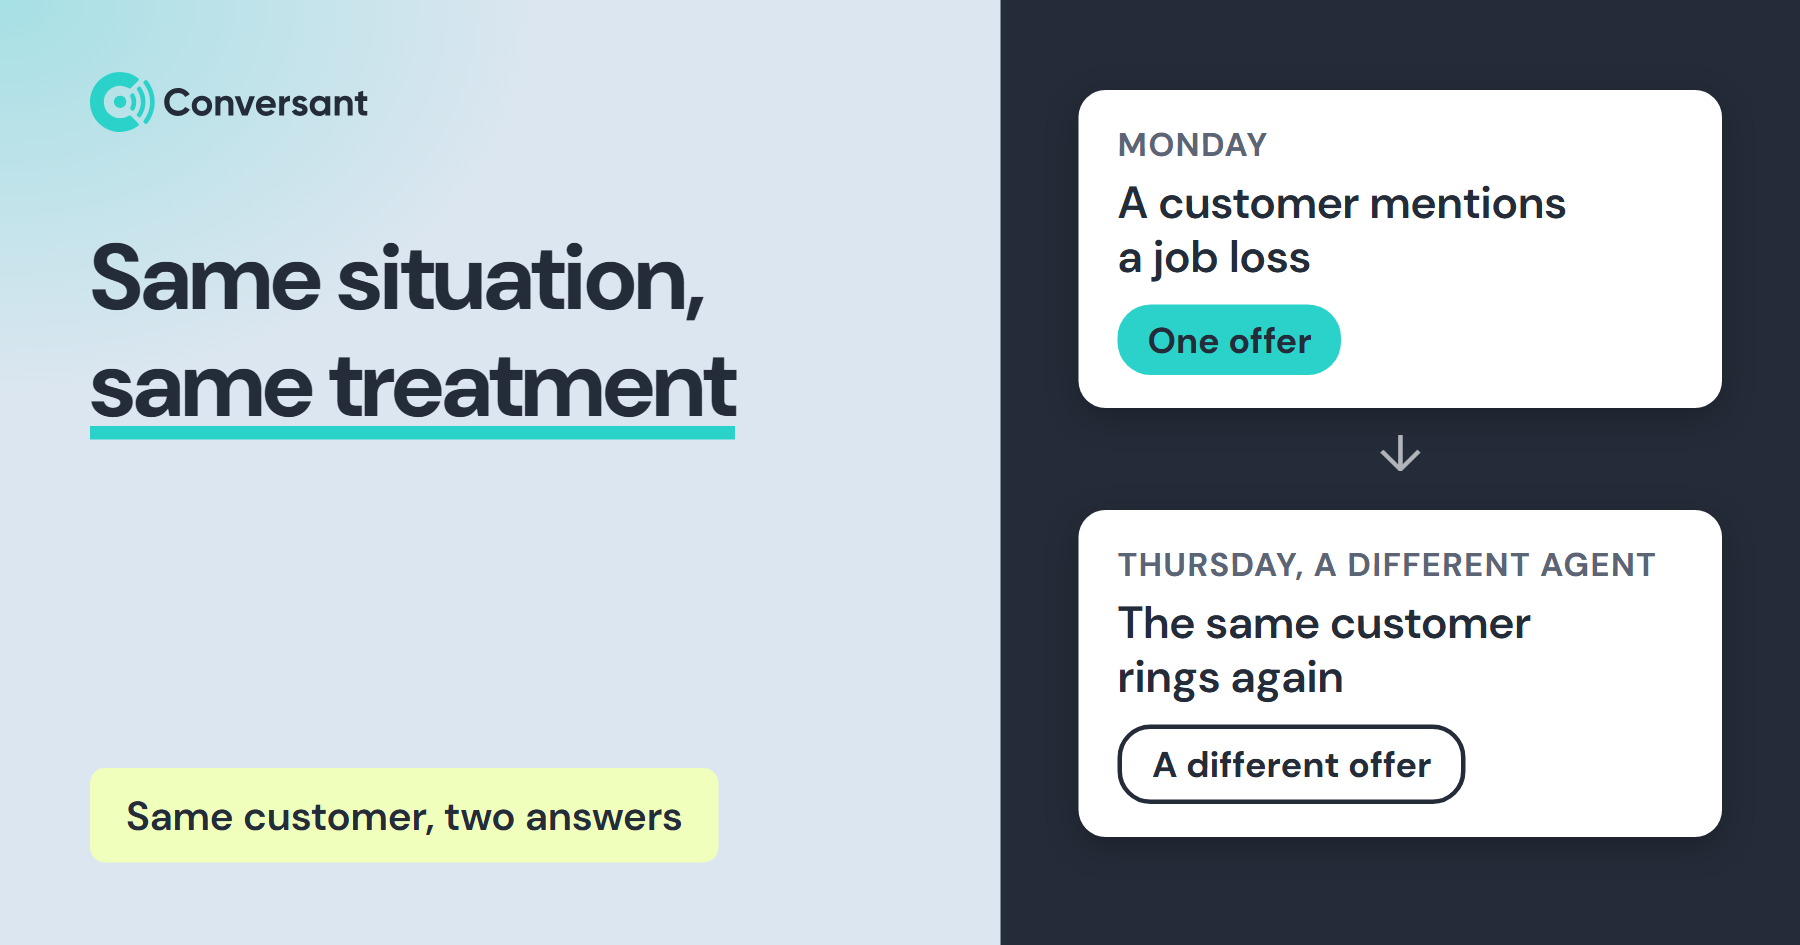
The first deadline for motor finance not owed notices is 18 November 2026. Say a customer reads theirs on a Saturday, disagrees with it and rings your contact centre on Monday morning. Whatever the agent says next has to match the letter, so check now that your letter, your scripts and every person who might pick up the phone give the same answer.
A letter is one fixed piece of text. A call is a conversation, and each agent will put the answer in their own words unless the team has agreed the words in advance.
A letter is one fixed piece of text. A call is a conversation, and each agent will put the answer in their own words unless the team has agreed the words in advance.
When motor finance not owed notices are due, and who gets one
The FCA published its statement on the motor finance scheme on 2 July 2026. It says that "lenders will need to tell you if you have complained and are not owed compensation under the scheme", and it sets these deadlines:
- 18 November 2026, if the agreement began on or after 1 April 2014 and the customer complained by 30 June 2026.
- 18 January 2027, if the agreement began before 1 April 2014 and the customer complains by 31 August 2026.
- Within 5 months of receiving the complaint, for complaints made after those dates.
So the notices carry on after 18 November. The second group follows in January, and each later complaint gets its own five-month deadline. The FCA also lists some exceptions, so check its page, and your own compliance or legal people, for how they apply to your customers.
Why the call after the letter matters
Say three customers get the same letter and ring on the same afternoon. They reach three different agents. If the agents explain the letter in three different ways, each customer is left with two versions from the same lender, the one in the letter and the one on the phone.
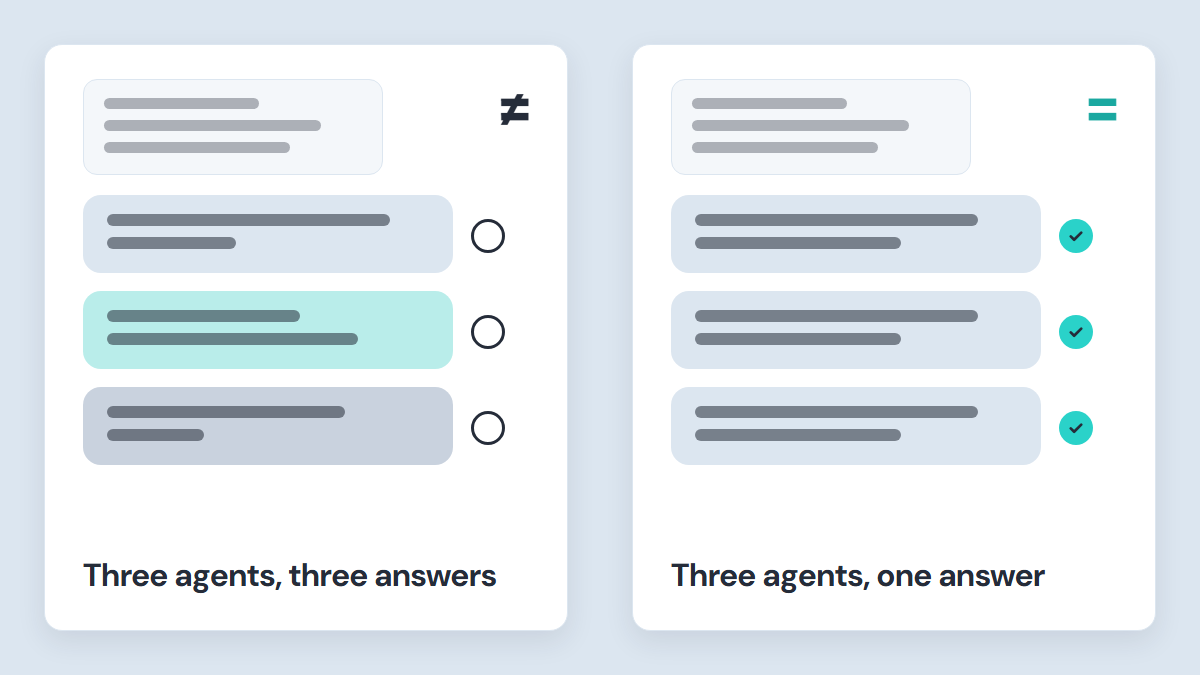
We'd start from the questions a customer is most likely to ask: why am I not owed anything, what happens next, and what can I do if I disagree. We'd treat the answers as a consistency problem and fix it before the letters land. Agree the words once, put them everywhere a customer might hear them, and then check the calls.
A checklist for the weeks around 18 November
Work through these in order. The first four are the ones to finish before the letters go.
What isn't settled yet
The scheme is partly suspended. The FCA says the Upper Tribunal will hear the legal challenges "on 14 to 18 December 2026 or 16 to 26 February 2027", and that the final dates depend on whether anyone applies for further expert opinion or disclosure and whether that application succeeds. Check the FCA's page for the current window.
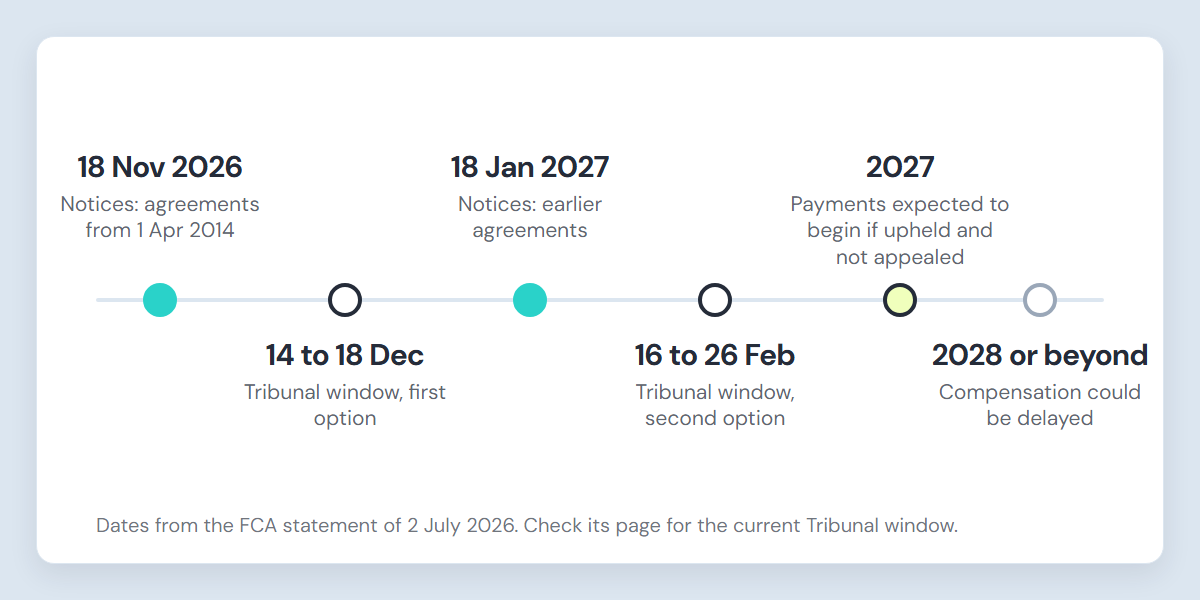
If the scheme is upheld and the judgment isn't appealed, the FCA expects payments "to begin in 2027". It also says compensation could be delayed until "2028 or beyond". The page doesn't list which parts of the scheme are suspended. It does say firms "are not required to calculate or pay redress, or send communications about compensation owed under the scheme". We read the "not owed" deadlines as staying in place, but that's a question for your own compliance or legal people.
We take no view on the scheme itself. This piece is about being ready to talk to customers, whichever way the Tribunal decides.
We take no view on the scheme itself. This piece is about being ready to talk to customers, whichever way the Tribunal decides.
Where we fit
We help lenders look at how their customer conversations on the scheme actually run today and fix what we find, so every answer matches the letter. We're happy to talk it through.
Source: Financial Conduct Authority, "Motor finance scheme partially suspended", statement, first published and last updated 2 July 2026, read on 9 November 2026.